The Loan Is Paid Off. Where's My Title?
- PublishedSep 28, 2026
- Last verifiedSep 28, 2026
- Sources11
- 13 min read

Explore clearer car-buying guidance, market context, and ownership knowledge in one place.
A zero auto-loan balance does not always mean a paper title is already in hand. Newsletter 43 follows the separate payoff, lien-release, state-record and title-delivery steps that determine whether the vehicle is actually transfer-ready.
Decide First
One of the strangest moments in vehicle ownership arrives after the last payment, not before it. The lender portal says $0.00. The automatic payment is gone. The loan account may even show closed. Then you look for the title and realize you do not have one in your hand.
That can feel wrong because the financial story sounds finished. In practice, several separate systems may still have work to do. The lender has to recognize the debt as satisfied. The lienholder has to release its security interest. The motor vehicle agency has to update the vehicle record. The title may have to be printed, mailed, retained electronically or requested by the owner depending on the state. If you are selling or trading the vehicle, the next transaction may have its own document path.
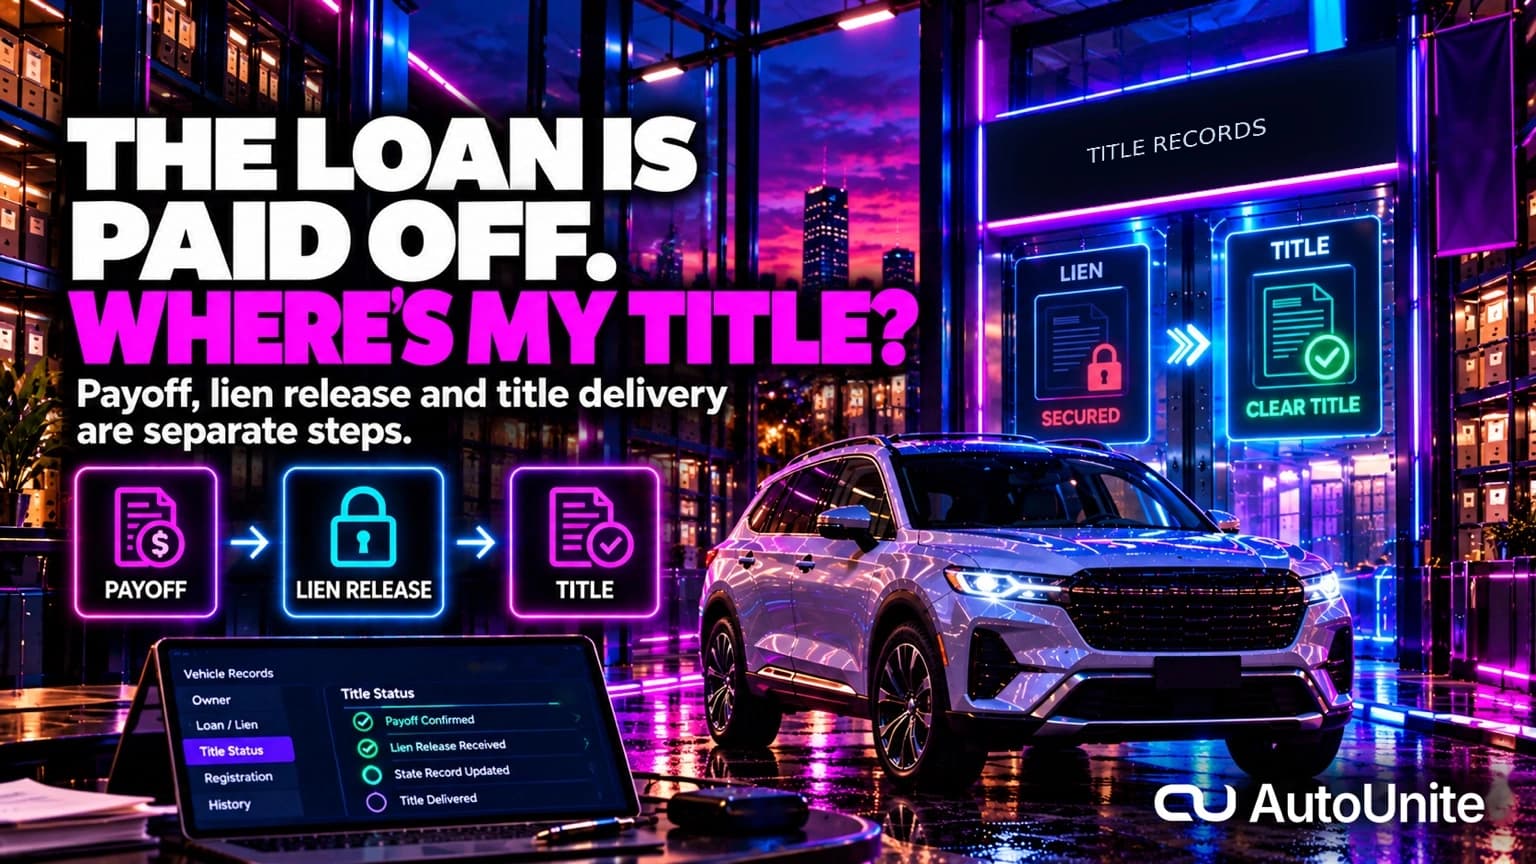
The key idea for Newsletter 43 is simple: payoff is a financial event. Lien release is a title-record event. Title delivery is a document event. Transfer readiness is a transaction event. They are connected, but they are not always simultaneous.
That distinction matters most when time suddenly matters. A private buyer is ready. A dealer is waiting on a trade. You are moving to another state. You need a duplicate after losing paperwork. Or you simply want the vehicle record cleaned up while the lender still exists under the name you remember.
A clean post-payoff workflow is easier to understand if you stop treating the title as one envelope that appears automatically and instead track four finish lines.
1. The debt is satisfied. The lender has received enough money to close the obligation. If the loan is being paid off as part of a trade, the actual payoff amount can differ from a statement balance because timing, interest and charges can affect the amount required to satisfy the loan. CFPB specifically tells consumers trading a financed vehicle to obtain the payoff amount rather than assuming the displayed balance is the final number.
2. The lien is released. The lender communicates that its security interest is satisfied. In an electronic lien and title system, that message may travel directly to the state motor vehicle agency. In other cases, the lender may mark a paper title, issue a release letter or use another state-approved method.
3. The state record is updated. The title record has to reflect the release. This step is important because a paper in your possession and the state's record can diverge. Virginia provides an unusually clear example: if a non-electronic lender marks a paper title satisfied and mails it to the owner, Virginia DMV says that action alone does not remove the lien from DMV records. The owner must take the additional step required by the state.
AutoUnite content is educational and research-focused. Vehicle information, pricing, ownership costs, maintenance, recalls, and other details may vary by region, dealer, and time.
4. The title is available in the form needed for the next transaction. That might mean a paper title arrives automatically. It might mean the title stays electronic until you request paper. It might mean you retain a title plus separate lien-release evidence. It might mean a dealer can use an electronic process that looks different from a private-party sale.
When an owner says, 'I paid off the car, so where is my title?' the useful answer starts by identifying which of these four finish lines is still open.
A paper title used to be the mental model almost everyone carried: pay off the lender, get the paper. Electronic lien and title systems changed that model.
AAMVA describes Electronic Lien and Title, or ELT, as a system for motor vehicle agencies and lienholders to exchange lien information electronically, including releases when loan requirements have been satisfied. AAMVA also encourages jurisdictions to keep title records electronic after lien satisfaction when their laws allow it rather than printing paper automatically.
That means the absence of paper can mean very different things. In one state it can mean the lienholder has not released the record yet. In another, it can mean the record is already clear and the state simply keeps the title electronic until the owner needs paper. In a third, a paper title may already be in the mail.
So the better question is not, 'Did a paper title show up?' It is, 'What does my state's title record show, and what form of title does this state issue after lien satisfaction?'
Virginia DMV publishes two different outcomes after the same basic event, paying off the vehicle loan.
If the lender participates in Virginia's Electronic Lien Program, the lender electronically releases the lien with DMV. Virginia says DMV records will no longer show the lien and a new title will be mailed to the owner's address on record. In that electronic path, DMV says the owner does not need to take additional action.
If the lender does not participate in the Electronic Lien Program, the lender can mark the title to show the lien is satisfied and mail the title to the owner. But Virginia warns that this does not remove the lien from DMV records. To clean up the state record and receive a substitute title, the owner must submit the required title and fee through the state process.
This is the type of behind-the-scenes difference that makes two friends give each other conflicting advice even when both are telling the truth about their own experience. One lender can create an electronic release and automatic print. Another can create a paper release that still requires an owner action.
Virginia also urges owners not to ignore an old recorded lien after receiving a paper release. If that title later disappears, obtaining another release can be harder if the lender has changed names, merged or gone out of business. That makes post-payoff cleanup more than paperwork neatness. It is future transaction insurance.
The state-by-state differences are not edge cases. They are the reason a national article should avoid promising one universal timeline.
California: California's ELT program keeps participating lienholders' title information electronically. When the lien is satisfied, DMV says the title is issued to the registered owner or a new lienholder if one is being added. California's registration procedures manual says the average time to receive a paper title from an electronic transaction is eight days, while pending record issues can push a case into manual processing.
Florida: Florida's current lien-satisfaction procedure says that if an electronic lien is satisfied and the lienholder does not request paper, the title remains electronic until the registered owner requests a paper title. In other words, the lien can be gone while no paper title is automatically traveling through the mail.
New York: New York's lender title guide says lienholders must release a lien when the borrower fully repays the loan. ELT participants release electronically. After the owner receives the release, the owner can apply for a new title without the lien. The release and the replacement title are related steps, not the same object.
Maryland: Maryland uses electronic lien processing and its current title guidance reflects a move away from automatically printing a clean duplicate title after an electronic lien release. A customer can request a clear title through Maryland's available channels when a paper copy is needed.
None of these systems means one state is 'better.' They show why the owner needs the rule for the jurisdiction that actually owns the title record.
Most owners do not think about lien-release workflow on an ordinary Tuesday. They think about it when the vehicle has to move into another transaction.
A dealer taking a trade may have electronic payoff tools, title vendors and state-specific processes that let the store handle a lien while the customer is buying another vehicle. A private buyer does not have the same operating stack. An out-of-state transfer may add a second jurisdiction's requirements. A refinance can involve one lien being released while another is being perfected. An estate or donation can expose a title that was never cleaned up years earlier.
AAMVA points to faster lien-release handling as one of the operational benefits of ELT because delays in releasing a security interest can threaten the timely completion of a vehicle sale. Virginia's own electronic-lien documentation includes separate transactions for dealer payoff, title printing and distributive mailing. That is a useful clue: the industry has workflows for these handoffs because the handoffs are real work.
For a consumer, the practical lesson is not to learn every back-office transaction code. It is to verify that the chain has reached the state record before promising a buyer, dealer or family member that the vehicle is ready to transfer.
When a state prints a title after a lien is released, it has to send that document somewhere. Virginia's electronic-lien guidance says the new title is mailed to the owner's address on record unless an authorized process directs it elsewhere.
That makes a simple housekeeping step surprisingly important: verify the address tied to the vehicle record before or immediately after payoff, especially if you recently moved.
A title mailed to an old address can turn a clean electronic release into a replacement-title project. The loan can be closed, the lien can be cleared, and the owner can still be stuck chasing paper that went to the wrong place.
This is another reason to separate status from possession. 'DMV shows no lien' and 'I have the paper title I need for this sale' are two different questions.
The easiest mistakes are the ones that feel reasonable because the loan app looks finished.
Do not shred the payoff confirmation or lien-release evidence immediately. Keep it until the state record is clean and the title format you need is available.
Do not assume a zero displayed balance proves the title system was updated. Ask when the lien release was transmitted or issued and how your state receives it.
Do not advertise 'clean title in hand' if you do not actually have the document required for the transaction. A clear electronic record may be enough for some transactions, but a private sale or an out-of-state transfer may still need specific paperwork.
Do not borrow another state's rule. A Florida owner and a Virginia owner can both pay off a loan on the same day and have different next steps.
Do not wait years to reconcile an obvious mismatch. If the lender says the debt is satisfied but the state still shows an active lien, fix the mismatch while the lender's records and people are easier to reach.
Newsletter 43's decision object is not a generic title checklist. It is a handoff tracker built around the exact points where post-payoff status can get lost.
1. Payoff record
Record the lender, account reference, final payoff amount, date received and proof that the obligation is satisfied.
2. Lien-release record
Record the date the lender says it released the lien, whether the release was electronic or paper, and any confirmation or case number.
3. State-record check
Confirm whether the motor vehicle agency still shows a lien and note the date checked. Do not infer this from the lender portal.
4. Title-format check
Is the clear title supposed to remain electronic, print automatically, or require an owner request? Note the rule for the state that owns the record.
5. Delivery check
If paper is being mailed, confirm the address and expected path. If the state provides a way to request paper, record when that request was made.
6. Transfer-readiness check
Before a sale, trade, refinance or out-of-state move, confirm what the next transaction requires. A state record that is clear is excellent. The next transaction may still require a particular document.
7. Escalation log
If the chain stalls, record who you contacted, what they said, what reference number was assigned and the next promised action. That turns 'I have been calling everyone' into an evidence trail.
The spreadsheet cannot release a lien. It can do something more practical: keep the lender, DMV and transaction evidence connected until the title is actually ready for what you plan to do next.
Urgency changes the order of operations. Do not spend three days waiting for a mystery envelope before learning whether an envelope is even supposed to come.
Start with the lender: 'Has the lien been released? On what date? Was it transmitted electronically or issued on paper? Do you have a confirmation or release document?'
Then check the state process: 'Does my record now show no lien? Does this state keep the clear title electronic? If paper is required for my transaction, how do I request it?'
Then check the transaction: if you are trading, ask the dealer what title or payoff proof its state and title vendor require. If you are selling privately, use the motor vehicle agency's current seller guidance for that jurisdiction rather than assuming the dealer process applies to you.
The goal is not to rush the paperwork. It is to find the exact open gate. Waiting is rational when you know what process is running. Waiting is frustrating when no one has confirmed that the process even started.
This is not just a consumer inconvenience. A vehicle can be physically sitting on a dealer's lot while its ownership paperwork is still moving through payoff, lien release and title transfer.
That matters because a used-car department has money tied up in the trade, reconditioning can be underway, the vehicle may be photographed and priced, and yet the store still needs a valid title path before the next ownership transfer can be completed correctly.
AAMVA specifically identifies reduced time waiting for lien release as an ELT benefit for dealers. That operational reality is one reason a title clerk can care just as much as the customer about a release message that has not posted.
Good process is not 'trust us, the title is coming.' Good process is knowing which party owns the next action and having proof that the handoff happened.
Paying off a vehicle is still a real milestone. It means the debt obligation is ending. It just does not guarantee that every downstream title task has already completed by the time the lender portal turns to zero.
Treat the final payment as the beginning of a short closeout process: confirm payoff, confirm lien release, confirm the state record, confirm title format, and confirm the document path required for your next transaction.
If all five are clean, you are not waiting on hope. You are holding a verified chain.
The final question is not, 'Why did the title not show up the day I paid off the loan?' It is, 'Which handoff is still open, and who owns it?'