The Trade Was Worth $28,000. The Payoff Was $34,884.
- PublishedSep 25, 2026
- Last verifiedSep 25, 2026
- Sources6
- 8 min read

Explore clearer car-buying guidance, market context, and ownership knowledge in one place.
Your trade value and loan payoff answer different questions. See how negative equity changes the next car loan and what the dealer is actually solving.
Decide First
The vehicle had value. The loan balance was larger.
The used-car manager finished the walkaround, set the appraisal sheet on the counter and wrote $28,000 in the ACV box.
The customer nodded. The SUV was clean, the miles made sense, and the number felt fair.
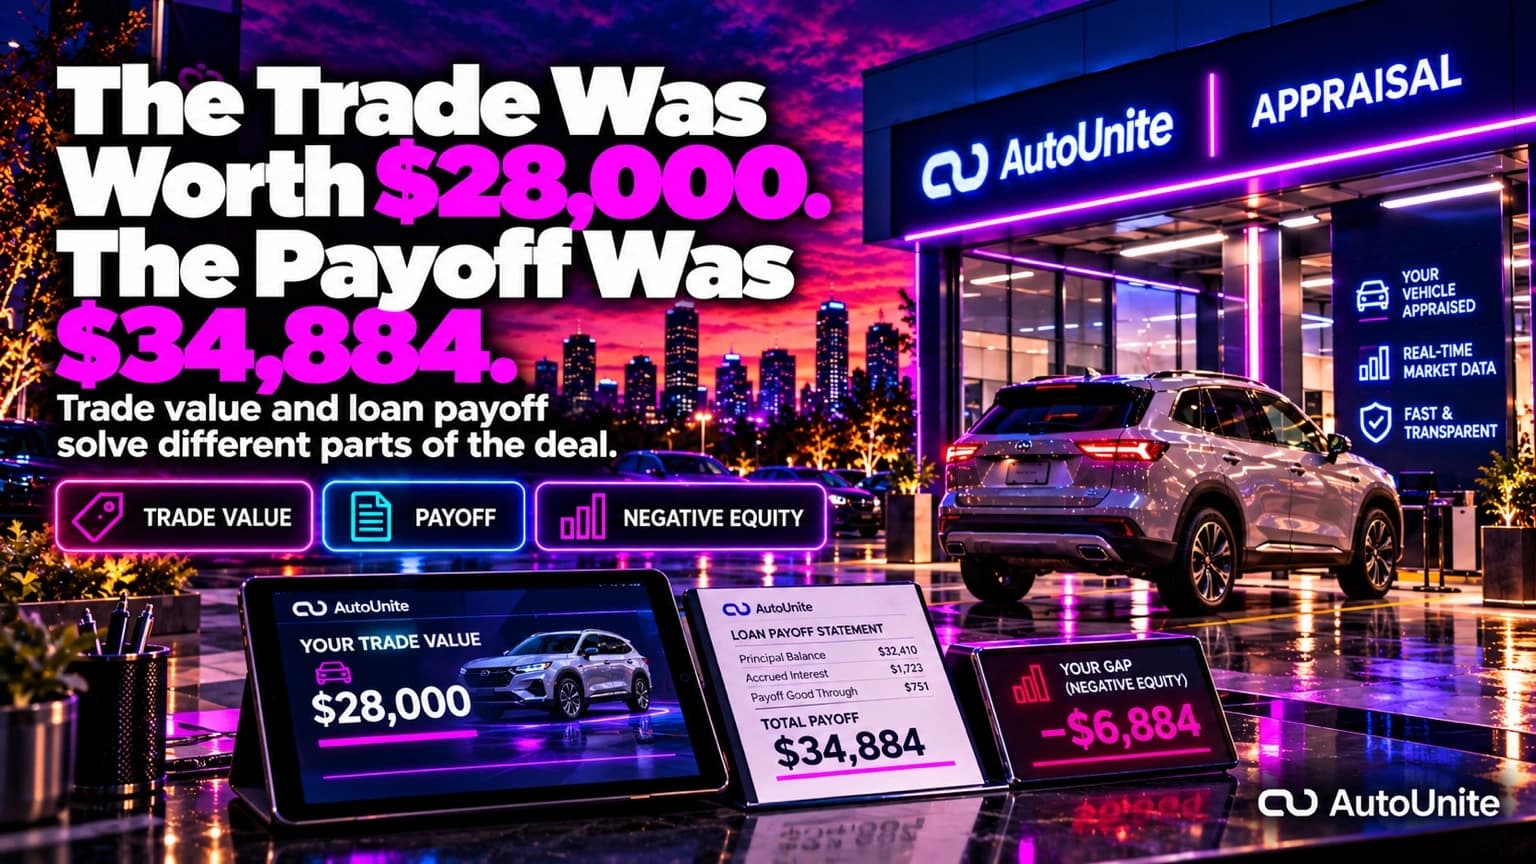
Then the salesperson pulled the ten-day payoff: $34,884.
The customer looked at both figures and asked, “So what happened to the twenty-eight grand?”
Nothing happened to it. The vehicle still had $28,000 of value. The lender simply had a larger claim against it.
The $6,884 gap existed before anyone selected the replacement vehicle, discussed cash down or quoted a payment.
This opening is a composite of a common dealership exchange. The figures are built around the Q2 2026 average negative equity reported by Edmunds; they are not presented as a named customer transaction.
ACV answers one question: what is the store willing to own the trade for today?
The payoff answers another: what must reach the current lender to release the lien?
Put those lines together and the trade position is simple:
The trade is not worthless. It is $6,884 short of clearing its loan. That is the distinction the customer needs before the next pencil means anything.
Edmunds’ Q2 2026 report found that 29.6% of trade-ins attached to new-vehicle purchases carried a deficit; the mean shortfall was $6,884. Those figures anchor the composite; they are market statistics, not a named customer file.
For transactions that rolled an underwater trade into the next new-vehicle loan, Edmunds reported an average monthly payment of $944 and projected lifetime interest of $16,270.
AutoUnite content is educational and research-focused. Vehicle information, pricing, ownership costs, maintenance, recalls, and other details may vary by region, dealer, and time.
Those figures describe a market pattern, not a prediction for every customer. Credit profile, vehicle, term, rate, cash, taxes, fees and lender structure still determine the actual deal.
Negative equity is common enough to be a major dealership issue, but it is not the condition of every trade. Edmunds reported that 68.8% of trade-ins toward new-vehicle purchases carried positive equity in Q2 2026, with an average positive-equity amount of $13,330.
That broader context matters. The store should not assume a customer is buried simply because the loan is long, and the customer should not assume a strong appraisal automatically means there is money available for the next deal. Equity only appears after value and payoff are put on the same line.
The appraisal tells you what the vehicle contributes. The payoff tells you what the lien consumes. The difference is the position.
The store may send the full $34,884 to the old lender. That action clears the title; it does not create $6,884 of new equity.
FTC guidance on negative-equity trade-ins warns that a promise to pay off an old loan can be misleading when the shortage is actually added to the next loan or taken from the customer’s down payment.
Dealer language should keep the two ideas separate: the prior lien will be satisfied, and the difference still has to be handled in the structure.
The fastest way to make negative equity feel suspicious is to jump straight from appraisal to a new monthly payment. The cleaner path is to follow the old debt as its own line.
Start with the composite in this story:
| Line | Amount | What it means |
|---|---|---|
| Trade value / ACV | $28,000 | What the store is allowing for the SUV today |
| Ten-day payoff | $34,884 | What the existing lender needs to release the lien |
| Equity position | -$6,884 | Debt not covered by the trade value |
If the customer pays the full $6,884 shortage separately, that old debt does not need to ride into the replacement loan. If the customer contributes $2,000 toward it, roughly $4,884 remains. If a lender allows the entire shortage to be rolled forward, the next amount financed grows before taxes, fees or optional products are considered.
The FTC and CFPB both tell shoppers to watch this step because a promise to “pay off” the old vehicle can be misunderstood as a promise to erase the debt. The old lender can be paid in full while the shortage is still carried by the customer in the next contract.
CFPB explains loan-to-value as the amount borrowed compared with the value of the vehicle securing the loan. Its simple example is $20,000 borrowed on a $20,000 vehicle: 100% LTV. Add old debt and the amount borrowed can move above the replacement vehicle’s value.
That does not create one universal lender ceiling. Each lender and program can treat advance, collateral, credit, income and term differently. It explains why the desk may suddenly ask for cash, a less expensive vehicle, another term or another lender after the trade shortage appears.
The customer hears: “Why do you need more money down?”
The desk may be hearing: “This lender will not advance that much against this vehicle.”
Those are different sentences describing the same obstacle.
Rolling negative equity is not automatically irrational, and waiting is not automatically superior. A customer whose current vehicle is unreliable, unsafe for the household’s needs or expensive to keep may choose to absorb a known shortage to solve a larger problem. Another customer with a reliable vehicle and no urgency may decide that paying the balance down first is the cleaner financial move.
The dealership does not need to decide which life problem matters more. It needs to keep the $6,884 visible long enough for the customer to choose with the debt in plain sight.
Here is an illustrative comparison using $42,000 financed before the old shortage, a 7% APR and a 72-month term. It is not a dealership quote, lender approval or claim that every bank will accept the same advance.
After 36 scheduled payments, approximately $3,801 of that original shortage would still remain in the larger balance.
That is old debt traveling inside the next car loan. The payment may fit, but the equity problem did not reset at delivery.
CFPB explains that carrying an unpaid balance forward raises the next borrowing request. CFPB’s LTV guidance explains why a higher loan-to-value ratio can affect lender risk and financing terms.
That does not create one universal advance rule. Each lender, vehicle, credit file and deal structure can be different.
The desk still has to know what can actually be bought. A payment that looks acceptable on a worksheet does not help if the amount financed, LTV or customer profile falls outside the lender’s program.
No option makes the shortage free. The job is to show where it goes and what changes when the customer chooses a path.
Here is language that keeps the trade conversation straight:
“We own your trade at $28,000. Your lender needs $34,884 to release it, so we are $6,884 short before we build the replacement loan. I will show you the amount financed with that balance included, and then we can look at cash, another vehicle, another appraisal or waiting.”
That statement does not blame the customer, hide the payoff or pretend the store absorbed the shortage. It gives the salesperson and the desk the same starting point.
The used-car department establishes the ACV. The salesperson brings the payoff into the conversation. The desk shows the trade difference and the two structures. F&I confirms the contract terms and disclosures.
When one of those steps skips the shortage, the customer can reach the business office believing the trade created money that was never there.
The clean handoff is not complicated: same ACV, same payoff, same $6,884 difference, same amount financed.
That problem may be manageable. It may also be the reason to change the vehicle, the cash or the timing.
Either way, the first honest payment presentation starts with the trade difference in plain sight.
Dealers: where do you show the shortage on the first worksheet—beside ACV, above the amount financed or inside the payment explanation?
Before discussing the next payment, put four numbers on one sheet: current trade value, current payoff, equity or shortage, and the amount financed on the replacement vehicle before that shortage is added.
That one view prevents the trade from becoming a magic trick. The customer can see that the $28,000 did not disappear. The dealer can show exactly where the $34,884 payoff went. And if the next loan is too large, both sides can work on the real problem instead of arguing about the appraisal.