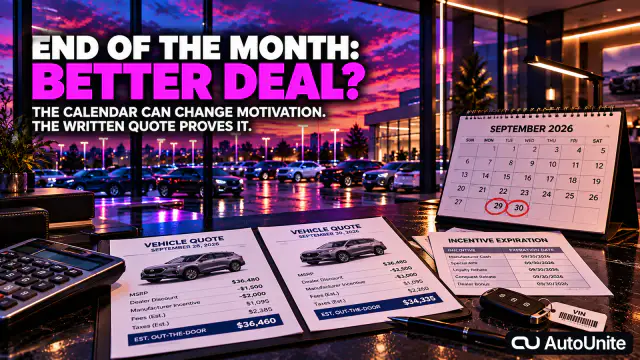
A Month-End Deal Board that separates market price, published program deadlines and possible store motivation, then measures the final clean deal against a written baseline.
Decide First
The last day of the month is not a coupon code.
It can matter. Sometimes a lot.
But the useful part of month-end shopping is not guessing whether a salesperson is one car away from a bonus. You usually cannot know that. The useful part is recognizing that several clocks can be running at once, then separating the one you can verify from the ones you cannot.
A dealer may have a monthly objective. A manufacturer program may expire. A specific vehicle may be aging. A competing store may have already put a better number in writing. Your preapproval may expire next week. Your trade could move in value. The exact car you want could sell tonight.
Those are different pressures.
Treating all of them as “the end of the month” is where car-buying folklore gets sloppy.
AutoUnite’s approach is simpler: use the calendar as a possible tailwind, then make the written deal prove the savings.
There is a real business reason month-end can change a dealership’s behavior.
Dealerships and sales teams work against goals. Depending on the brand, store, period and compensation plan, those goals can involve unit volume, model mix, quarterly performance, individual salesperson thresholds, manufacturer programs or internal targets.
Edmunds notes that a dealership can become more motivated near month-end if it is a few cars short of a quota tied to a meaningful bonus. It also makes the equally important point that the effect can disappear if the store has already met its goal.
Same date. Different economics.
That is the part most “best day to buy a car” advice leaves out.
The shopper can see the date.
The shopper usually cannot see the store’s actual objective, how close it is, whether a specific sale qualifies, or whether the target has already been reached.
So the invisible target should never become the foundation of your negotiation.
It is a possible explanation for extra flexibility. Nothing more.
Comments are shopper discussion, not verified article evidence.
Comments are not open on AutoUnite yet. Published articles and Ask AutoUnite are the current way to get answers.
AutoUnite content is educational and research-focused. Vehicle information, pricing, ownership costs, maintenance, recalls, and other details may vary by region, dealer, and time.
The cleanest way to use month-end is to build a baseline before the last-day pressure arrives.
For one exact VIN, write down:
Then calculate one number:
Verified timing gain = best clean baseline deal minus the final clean month-end deal.
The word clean matters.
If the price falls $900 but the dealer adds a $1,295 product, the calendar did not save you money.
If the selling price improves while your APR rises enough to add more interest than the discount, the structure changed.
If the trade allowance rises by $1,500 while the vehicle discount falls by the same $1,500, the economics did not improve.
The Month-End Deal Board forces all of that onto one page.
This is the price the market will support today for the exact or truly comparable vehicle.
You establish it with competing written quotes, comparable inventory, verified incentives and the actual VIN.
This is your baseline.
Without it, “$2,000 off tonight” can sound impressive even when another store was already $1,500 cheaper yesterday.
Manufacturer incentives have real start and end dates.
Cash support, special APRs, lease programs, loyalty offers and model-specific promotions can change at a month boundary. Current offer pages commonly show defined expiration dates and eligibility conditions, and the FTC advises shoppers to get the offer details and discounts in writing.
This clock is verifiable.
If a published program ends September 30, that is an actual deadline for the current program. It does not prove the next program will be worse. It proves only that today’s known program ends.
That distinction keeps you from confusing evidence with prediction.
This is the one shoppers love to guess.
How many units does the store need?
Is the salesperson one deal from a bonus?
Does a certain model help the store hit a manufacturer objective?
Does quarter-end matter more than month-end?
Maybe.
But unless the dealership tells you and you have a reason to trust the explanation, this clock is mostly invisible.
You do not need to solve it.
If the final written deal suddenly becomes materially better, capture the improvement. You are buying the result, not the story behind it.
The FTC recommends getting an out-the-door price in writing before you visit the lot and before discussing dealer financing.
That guidance becomes even more valuable when a deadline is involved.
Month-end can make many numbers move at the same time:
A monthly payment can fall while the total cost rises.
A trade allowance can improve while the vehicle price worsens.
A “special discount” can be offset by an accessory that was not in yesterday’s quote.
Written out-the-door quotes remove most of that fog.
Compare the same VIN, same taxes, same required fees and same optional-product assumptions. Then compare financing and trade separately.
As of late September 2026, the national new-vehicle market is not behaving like every dealer is desperate for every sale.
Cox Automotive reported 2.68 million new vehicles in inventory at the end of August, equal to about 73 days’ supply, while retail demand remained healthy and inventory had declined for a third consecutive month. Cox also said franchised dealers reported less pressure to reduce prices. Its September sales forecast projected a roughly 16.3 million SAAR and year-over-year sales growth for the month.
Kelley Blue Book reported the August 2026 average new-vehicle transaction price at $50,089, with incentive spending averaging 6.5% of transaction price, down from 7.2% a year earlier.
Those are national measurements, not a price guide for your exact car.
That is the point.
A scarce hybrid in your market can be firm on the 31st. A slow-moving configuration can be negotiable on the 12th. The national average and the wall calendar are context; the exact VIN is the transaction.
A vehicle that arrived yesterday and a vehicle that has been sitting for months are different assets to a dealership.
Age can change how urgently a store wants to move a unit because inventory ties up capital and market conditions move around it.
That pressure is not identical across every car on the lot.
A shopper may find one vehicle with meaningful flexibility while the nearly identical vehicle parked beside it is priced firmly.
For new cars, local supply, color, package, powertrain and model-year transition all matter.
For used cars, the effect is even more VIN-specific because every unit has its own acquisition cost, reconditioning history, mileage, condition and wholesale alternative.
If you can verify days on market or listing age, add it to the Month-End Deal Board as context. Do not treat it as a guarantee of discount.
Month-end folklore often treats new and used cars as though they operate under one pricing system.
They do not.
Edmunds’ current 2026 used-car timing analysis says its sales data has shown the strongest seasonal used-car discounts in October and November. That is a seasonal pattern in Edmunds’ dataset, not proof that the last day of each month is cheapest.
A used manager might be eager to move one 90-day-old SUV while holding firm on a fresh trade that is already priced below nearby comparables.
The useful question stays the same:
Did the final deal on this VIN improve against a real baseline?
March, June, September and December end quarters.
December also ends the calendar year and often overlaps with outgoing model-year inventory.
That can place multiple business periods on top of one another.
It can increase the chance that a store has a reason to stretch.
It can also produce the opposite problem: less selection.
The last remaining vehicles may not have the color, package, drivetrain or equipment you actually want.
A bigger discount on the wrong car is not a better purchase.
The more specific your must-have configuration, the more you should value availability alongside price.
When someone says, “This deal is only good tonight,” ask one question:
What exactly changes tomorrow?
A useful answer has a noun attached to it:
A vague answer is just urgency.
Urgency is not automatically dishonest. A store may genuinely have extra flexibility today.
But the buyer should know whether the pressure comes from a published economic event or from the seller’s desire to close now.
You can respond to either one without surrendering the structure of the deal.
This is an illustrative example, not an AutoUnite customer case.
A shopper has already narrowed the purchase to one exact vehicle.
Best competing clean out-the-door quote: $39,180
Dealer’s earlier clean quote on the preferred VIN: $39,450
Dealer’s final month-end clean quote: $38,650
Same incentive eligibility.
Same required fees.
No new add-ons.
Same financing terms.
Trade is kept separate.
The final month-end quote beats the strongest existing baseline by $530.
That is a measurable timing gain.
The shopper does not need to know whether the store was one unit short, five units short or already past goal.
The written offer did the work.
Another shopper sees the vehicle price fall from $37,900 to $37,200 on the final day.
Looks like a $700 win.
Then the final worksheet includes a $1,295 mandatory protection package that was not in the earlier quote.
The net transaction is now $595 worse before even considering financing.
If the APR also moved against the buyer, the gap grows.
This is why the calendar is a weak decision tool by itself.
It highlights a moment to negotiate.
It does not audit the deal for you.
The final afternoon of the month is a poor time to figure out whether you actually like the car.
Test-drive earlier.
Check insurance earlier.
Get your financing preapproval earlier.
Get a real trade value earlier.
Compare trims and equipment earlier.
Research the exact model-year differences earlier.
Then, if timing allows, reopen price discussions near the end of the period.
You are using the deadline for negotiation, not for discovery.
That changes the entire experience.
A prepared buyer can act quickly without being rushed.
Closing time should not decide your financing.
A bank or credit-union preapproval gives you an APR, term and borrowing limit before the dealer’s finance office enters the picture.
The dealer can still beat it.
Great.
But if it cannot, you already have a reference point.
That prevents an apparent vehicle-price win from being quietly repaid through worse credit terms.
The same principle applies to the trade.
Know the payoff.
Know an outside buy offer.
Know the equity.
Keep enough separation between the vehicle price, trade and financing to see what actually changed.
I would not let a calendar theory override the purchase if:
There is no prize for buying on the 31st.
The goal is the right car under a strong, understandable deal.
Waiting can be rational when:
That is a shopper with options.
Options are the real leverage.
Before signing, fill five boxes.
Make sure every quote refers to the same vehicle or a truly comparable alternative.
Record the best written out-the-door offer already available.
Record the incentive, APR or lease-program expiration you can actually verify.
Confirm price, fees, add-ons, trade, APR, term and amount financed.
Calculate whether the final deal is genuinely better than the clean baseline.
If the number is positive and the vehicle still fits, month-end helped.
If the number is zero, the calendar created noise.
If the number is negative, urgency made the deal worse.
Dealers do not need fake theater to use real flexibility.
If the store wants one more delivery, a simple statement is enough:
“We have more room on this vehicle today.”
Then put the improved number in writing.
That is easier for the shopper to trust than a story about a manager “losing money” or a mystery buyer arriving in ten minutes.
Strong deals survive documentation.
Stop walking into the store at closing time announcing that you know the dealer “needs one more car.”
You probably do not know.
Do not assume the salesperson is desperate.
Do not make an impossible offer because the month ends in three hours.
Bring leverage that exists whether the store has a quota or not:
Then let month-end reveal whether there is extra room.
Month-end matters for one reason: sometimes business objectives make the next deal worth more to the seller than it was a week earlier.
That can create opportunity.
But the shopper cannot see the objective, cannot predict tomorrow’s incentive and cannot assume the exact VIN is negotiable simply because the date changed.
What you can see is the paper in front of you.
The written out-the-door price.
The incentive expiration.
The APR.
The trade.
The add-ons.
The exact car.
The calendar can change motivation. The written quote proves whether it changed your deal.
This issue uses Edmunds car-buying timing guidance for the month-end mechanism and current 2026 used-car seasonality; Federal Trade Commission guidance for written out-the-door pricing, incentives and financing comparison; and current September 2026 Cox Automotive and Kelley Blue Book reporting for national inventory, transaction-price and incentive context.
Dealer quotas, salesperson bonuses and manufacturer-to-dealer objectives vary by store, brand and program and are frequently not public. AutoUnite does not assert that any specific dealership is chasing a target without direct evidence. AutoUnite internal OTD snapshot collections were reviewed but not used for consumer claims because sampled records contained protective fallback/estimated fee authority rather than canonical dealer-fee truth.