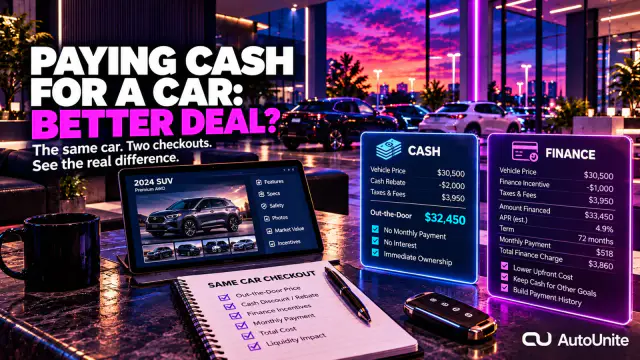
A Same-Car Checkout that separates the written out-the-door price, payment-method incentives, borrowing cost and liquidity before choosing cash or financing.
Decide First
A cashier's check feels like leverage.
You are ready to buy. There is no loan approval to wait for, no monthly payment to discuss and no interest bill coming later. So it is natural to expect the dealer to reward that simplicity with its lowest price.
Modern auto retail does not work that neatly.
The Federal Trade Commission tells shoppers to get the out-the-door price in writing before discussing dealer financing. Edmunds makes the reason for this article even plainer: cash customers are generally no more attractive to a dealership than buyers who finance, and dealer-arranged financing can itself create revenue for the store. FTC - Financing or Leasing a Car Edmunds - Can I Get a Better Deal Paying Cash for a Car?
Cash can still be the cheaper way for you to own the car. It eliminates auto-loan interest on the money you do not borrow. It may also qualify for a cash incentive that cannot be combined with promotional financing.
But that is different from saying cash automatically buys a lower selling price.
The clean question is:
What does this exact vehicle cost under each payment path after the incentives and financing costs are separated?
That is the comparison AutoUnite calls The Same-Car Checkout.
A shopper can accidentally negotiate three things at once:
That creates room for one number to improve while another gets worse.
The FTC's advice is deliberately boring and extremely useful: ask for the out-the-door price in writing before you arrive and before you discuss dealer financing. The out-the-door figure should show the total vehicle transaction before financing, including taxes and fees, and any discount should come with its eligibility conditions. FTC - Car Dealer Ads and Promotions
Comments are shopper discussion, not verified article evidence.
Comments are not open on AutoUnite yet. Published articles and Ask AutoUnite are the current way to get answers.
AutoUnite content is educational and research-focused. Vehicle information, pricing, ownership costs, maintenance, recalls, and other details may vary by region, dealer, and time.
For a cash-versus-finance decision, ask the dealer to make one extra distinction explicit:
Which incentives change depending on how I pay?
That is the part a single headline price can hide.
A useful written quote should make these items visible:
Once those numbers are fixed, payment method becomes a second decision instead of a negotiating fog.
A common mental model is that the dealership would rather receive your money immediately than wait years for loan payments.
The dealership normally is not waiting years.
With dealer-arranged financing, the dealership submits the credit application to one or more lenders. If the contract is accepted and funded, the lender provides the financing proceeds and the customer owes the lender. The FTC says dealerships typically profit from offering financing, and the negotiated APR can include compensation for the dealer's role in arranging the credit. CFPB guidance describes the lender's quoted buy rate and explains that a dealer may present a higher contract rate that includes compensation. FTC - Financing or Leasing a Car CFPB - What Is a Buy Rate?
That does not mean every financed transaction is more profitable, or that financing guarantees a lower vehicle price. Lender programs, manufacturer support, credit tier, dealership policy and the specific deal all matter.
It does explain why walking in with cash is not the bargaining trump card many shoppers expect.
The dealer can get paid on either path. Financing may also have economics of its own.
Put the same VIN into two columns and do not allow the vehicle itself to change.
| Cash path | Finance path |
|---|---|
| Written out-the-door price before payment-specific incentive | Written out-the-door price before payment-specific incentive |
| Cash / outside-finance incentive | Financing-specific incentive |
| Adjusted vehicle transaction | Adjusted vehicle transaction |
| Cash paid at delivery | Down payment |
| $0 amount financed | Amount financed |
| $0 auto-loan interest | APR and term |
| $0 finance charge | Total finance charge |
| Cash remaining after purchase | Cash remaining after down payment |
| Total dollars paid for the vehicle | Total of down payment + loan payments |
The first three rows answer a dealer-pricing question.
The next rows answer a financing question.
The liquidity row answers a household question.
Keeping those jobs separate prevents a very common mistake: treating a smaller monthly payment, a larger rebate or a cash purchase as proof that the whole transaction is cheaper.
1. Same-VIN out-the-door price. Not the advertised price. Not the monthly payment. The written transaction total.
2. Incentive difference. What cash, outside financing or dealer financing changes in the price.
3. Borrowing cost. APR, term, amount financed and total finance charge.
4. Cash left after closing. Not because a dealer should judge your savings account, but because a household can be debt-free and still be financially strained if the purchase empties its liquid reserve.
That is the entire framework.
A real September 2026 offer makes the mechanism easy to see.
Cars.com reported on September 18 that qualified buyers of a 2026 Hyundai Ioniq 9 could choose among different purchase programs, including a $7,000 rebate or 0% financing for up to 72 months. Cars.com specifically noted that the $7,000 rebate could not be combined with the 0% offer. It also reported a third path pairing the $7,000 rebate with 5.69% financing for up to 60 months or 6.39% for 72 months. Those offers were listed as valid through September 30, 2026. Cars.com - September Hyundai Ioniq 9 Deals
That creates three different questions:
Those are not the same calculation.
Cars.com's own example found that, for a borrower carrying the loan, the 0% path could beat the rebate-plus-higher-APR path over the full term. A literal cash buyer has a different comparison because there is no finance charge at all and the rebate reduces the amount paid today.
The lesson is not that one path always wins.
It is that the incentive menu can change when the payment method changes, so the checkout has to be rebuilt for each eligible path.
This is an illustrative scenario, not a current lender offer or a recommendation.
Assume the same vehicle has a written out-the-door price of $50,000 before payment-specific incentives.
Checkout A costs $3,000 less in nominal vehicle dollars. Checkout B leaves substantially more cash available on day one.
Neither sentence tells you which household decision is better.
Now suppose the buyer receives the same $3,000 rebate but finances the remaining amount after a $5,000 down payment:
The 6.35% rate is used here only as an illustrative rate input. Experian reported the average new-vehicle APR at 6.35% in Q2 2026, but actual approved rates vary materially by borrower, lender, term and vehicle. Experian - Average Car Loan Interest Rates
This is why an incentive should never be evaluated by itself. A rebate can reduce principal while the financing needed to use that path adds more than the rebate saved.
Even if you have enough money to buy the car outright, an outside preapproval can be useful.
It gives the decision a real price for borrowing.
The FTC and CFPB both encourage consumers who plan to finance to compare offers. CFPB also notes that the interest rate offered through a dealership is negotiable and may not be the lowest rate for which the buyer qualifies. CFPB - Can I Negotiate a Car Loan Interest Rate?
A cash-capable buyer can therefore walk in knowing:
That does not commit the buyer to a loan.
It turns “I hate debt” or “I want to keep my cash” into a priced decision instead of a slogan.
A trade can make a cash transaction look simpler than it really is.
Suppose the new vehicle is $42,000, the dealer offers $17,000 for the trade and the trade has a $5,000 payoff. It is easy for the conversation to collapse into one number: “You only need to bring $30,000.”
That hides several decisions.
The FTC recommends negotiating the vehicle price before the trade because a generous-looking trade offer can be offset by a different selling price. FTC - Financing or Leasing a Car
Keep these lines separate:
Then decide whether that final amount comes from your bank account or a lender.
Sometimes a shopper is told that financing unlocks a better price and that the loan can simply be paid off immediately.
That may be possible.
Do not assume it is free or unrestricted.
The CFPB says whether an auto loan can be prepaid without penalty depends on the contract and applicable state law. It tells buyers to check the Truth in Lending disclosures and the loan contract for a prepayment penalty before signing. CFPB - Can I Prepay My Loan Without Penalty?
If a financing-contingent discount is part of the deal, get the condition in writing and answer four questions before using the strategy:
A salesperson's “you can always pay it off” is not a substitute for the credit contract.
In everyday dealership conversation, “cash deal” often means no retail installment contract through the dealership. The actual funds might arrive by wire, personal check, certified funds or another accepted method.
Literal currency has its own compliance rules. The IRS says automobile dealers generally must file Form 8300 when they receive more than $10,000 in cash in a single or related transaction, and the federal definition of cash for this rule is more specific than ordinary conversation. A bank wire, for example, is not treated as cash for Form 8300 purposes. IRS - Motor Vehicle Dealership Form 8300 Q&A
So if you intend to pay without financing, ask the dealership before delivery which payment methods it accepts and when the funds are considered verified.
That is a logistics question, not negotiating leverage.
Cash eliminates auto-loan interest, but it also converts liquid money into a vehicle immediately.
The dealership cannot decide whether that tradeoff is right for your household.
A useful stress test is simple:
There is no universal “correct” emergency-fund number for a car purchase, and a newsletter should not invent one.
The important discipline is to price the loan first. If the approved APR is expensive, cash avoids an expensive obligation. If promotional financing is unusually cheap, the liquidity tradeoff looks different.
Current market data shows why this cannot be answered from memory. Experian reported average Q2 2026 APRs of 6.35% on new vehicles and 11.19% on used vehicles, with large differences by credit tier. Those are market averages, not a quote for any individual buyer. Experian - Average Car Loan Interest Rates
Your approved offer is the number that belongs in the checkout.
A customer should not need to reverse-engineer why the price changed when the payment method changed.
Show the same VIN in two columns.
Cash / outside-funds column
Dealer-finance column
If the two vehicle prices differ, label exactly why.
That makes the customer choose a payment method rather than guess which number moved.
“What's your cash price?” is not wrong. It is incomplete.
A stronger request is:
“Send me the written out-the-door price on this VIN, list every incentive and its payment-method condition, then show me the financing offers separately.”
That request works whether you expect to pay cash, finance, or have not decided yet.
Cash gives you certainty about one important thing: you will not pay auto-loan interest on money you did not borrow.
It does not guarantee the dealership's lowest price.
The strongest position is not “I have cash.”
It is knowing the same car's price, the incentive difference, the actual cost of credit and the amount of liquidity you are giving up before you choose how to pay.
What Matters: Get the same VIN's written out-the-door price and identify exactly which incentives change between cash, outside financing and dealer financing.
Watch This: A rebate can lower the purchase price while a higher APR adds more over time. A 0% offer can preserve cash while requiring you to give up a rebate. Dealer-arranged financing can create dealer compensation, so cash is not automatically stronger leverage.
Your Next Move: Complete the AutoUnite Same-Car Checkout with the actual cash incentive, approved APR, term, trade and amount financed. Choose the payment method only after every moving number is visible.