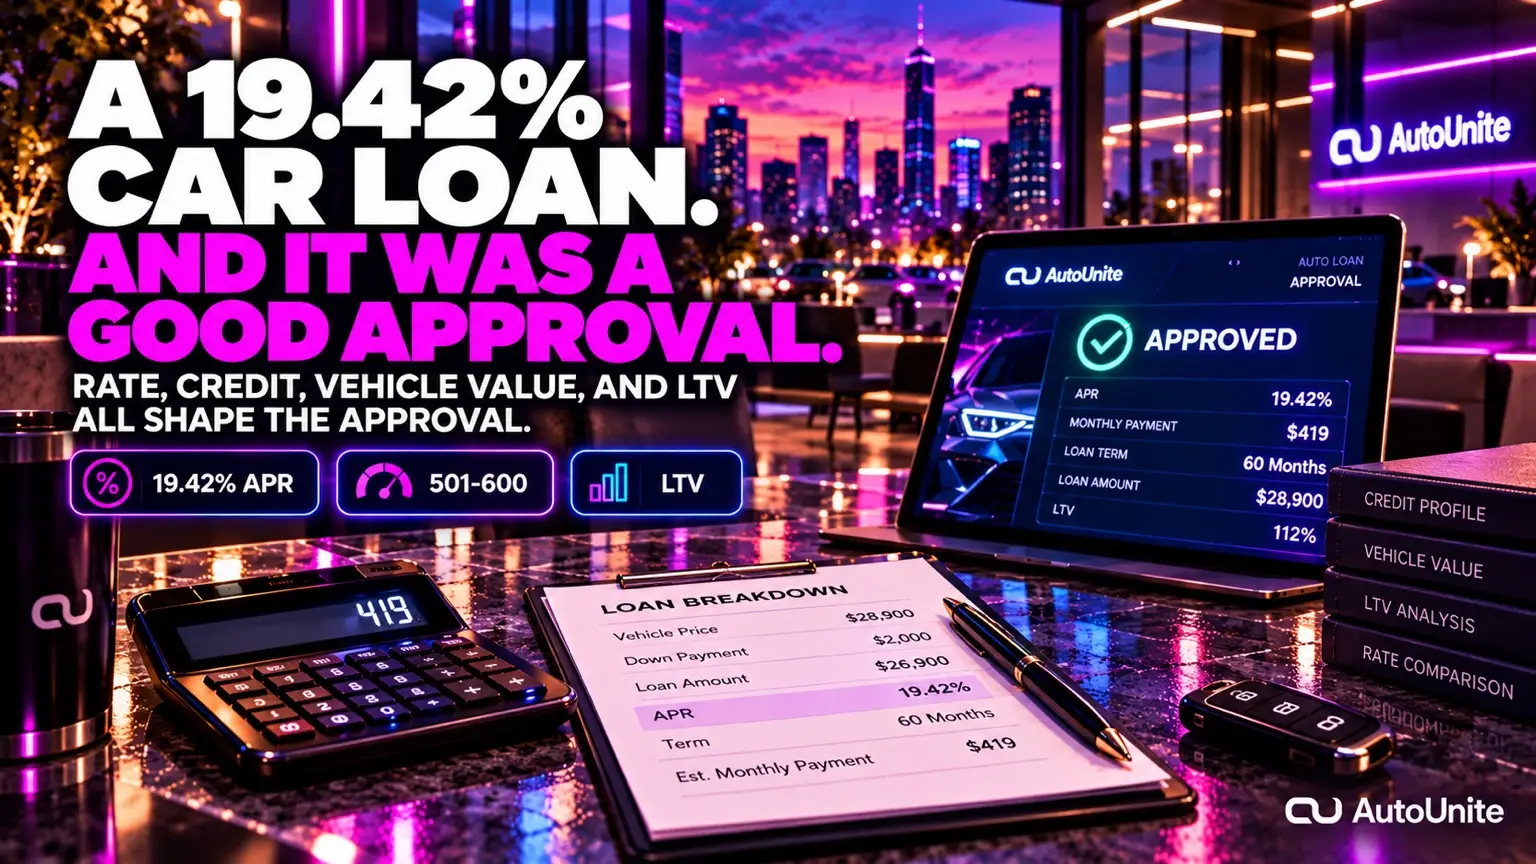
A 19.42% Car Loan. And It Was a Good Approval.
- PublishedSep 25, 2026
- Last verifiedSep 25, 2026
- Sources6
- 11 min read

Explore clearer car-buying guidance, market context, and ownership knowledge in one place.
A 19.42% APR is expensive. It can still be the strongest approval available when credit, vehicle value, negative equity and lender risk collide.
Decide First
A bad rate and a good approval can be true at the same time.
Why an expensive rate can still be a strong approval when credit, the vehicle, negative equity and lender risk all collide.
19.42% is a high APR.
I’m not going to pretend it isn’t.
If you walk into a dealership expecting a much lower rate and the finance manager puts 19.42% in front of you, I already know what you’re probably thinking:
How in the world is that a good approval?
That reaction makes sense.
But there’s another side of that desk.
Sometimes the customer sees 19.42%.
The finance manager sees the lender responses that already said no.
The desk sees the vehicle that wouldn’t finance.
They see the negative equity. They see the amount the lender is willing to advance.
They see the credit history underneath the score.
They see everything that had to move before one lender finally said yes.
And suddenly 19.42% can look very different.
The loan is still expensive.
It means a high APR and a good approval can be true at the same time.
I didn’t pick that number because it makes a good headline.
The 19.42% headline is preserved because it is the canonical historical story number. It also matches Experian’s published Q4 2024 average used-car APR for borrowers in the 501–600 VantageScore 4.0 band. The market has moved since then. Experian’s Q2 2026 data shows a 19.10% average used-car APR for 501–600, 13.93% for 601–660, and 21.62% for 300–500.
Those figures are benchmarks, not rate cards.
That doesn’t mean somebody with a 550 score automatically gets 19.42%.
There is no dealership rate chart that maps one credit score to one guaranteed APR.
The average for a score band is not an individual quote.
It doesn’t work like that.
The number is important because it shows just how far apart the financing world can be depending on the credit profile.
AutoUnite content is educational and research-focused. Vehicle information, pricing, ownership costs, maintenance, recalls, and other details may vary by region, dealer, and time.
Someone with excellent credit can look at 19.42% and think it’s insane.
Someone who has been declined by lender after lender can look at that same number and eventually realize:
This may actually be the approval I have available today.
That’s a very different conversation.
One of the biggest problems I’ve seen over the years is people walking into a dealership already convinced they know what their financing should look like.
They checked their score. They saw a rate advertised somewhere.
They ran a payment calculator. Now they believe the rest should be simple.
CFPB says lenders can weigh the applicant’s credit profile, income and debts alongside the loan request, term, cash down and vehicle. The lender is not looking at one number.
They may be looking at your payment history.
How much revolving debt you’re carrying. How much of your available credit is already used.
Your existing obligations. Your income.
How much you’re trying to finance. How much cash you’re putting down.
The term. And the vehicle.
Two customers can have credit scores that look similar and still be completely different deals.
One might have an old late payment and not much current debt.
Another might have multiple recent late payments, credit cards close to their limits, an existing car loan that’s behind, negative equity and no money down.
Similar-looking scores can hide very different credit situations.
That’s what gets lost when the entire conversation becomes:
“My app score looks better than this. Why isn’t my rate better?”
The lender sees more than that app score.
This one causes arguments in dealerships all the time.
A customer says: “That can’t be right. My Credit Karma score looks different.”
And the finance department is looking at something different.
That doesn’t automatically mean the dealership did anything wrong.
You don’t have one universal credit score that every lender in America sees the exact same way.
Credit Karma explains that it provides VantageScore 3.0 scores using Equifax and TransUnion data.
Auto lenders can use different scoring models, different versions and different bureau information. Some use auto-specific FICO models.
The current Experian benchmarks cited here use VantageScore 4.0.
So the score on your phone and the score involved in an auto-loan decision can be different.
That’s not something a finance manager should brush off.
They should explain it.
Because from the customer’s perspective, they walked into the store believing one thing about their credit and suddenly they’re being told something completely different.
Distrust starts quickly when nobody explains what is happening.
But the credit score still isn’t the part of auto financing I think shoppers misunderstand the most.
The car itself can completely change the deal.
This sounds backwards until you’ve worked these deals.
A customer is trying to make a responsible decision.
They’re thinking: I have credit problems. I should buy something older and cheaper.
Makes sense.
Except the lender doesn’t just look at the price on the windshield.
They’re also looking at what that vehicle is worth compared with how much money they’re being asked to lend.
CFPB defines LTV as the relationship between the amount borrowed and the vehicle value.
And it matters. Let’s say the customer already has negative equity in a trade.
FTC negative-equity guidance explains how an unpaid trade balance can be rolled into the next loan; that shortage still has to go somewhere.
Add that shortage to the amount being financed on an older vehicle and you can end up with a structure where the lender is being asked to advance far more than the vehicle supports.
That inexpensive car the customer thought would solve the problem can actually make the financing harder.
Behind the scenes, the dealership starts doing work the customer may never see.
You start pulling book after book.
What’s this one worth?
What does this vehicle look like to the lender?
What happens to the LTV here?
Does the mileage work?
Does the vehicle fit the lender’s program?
Can the negative equity fit inside this structure?
Can we keep the payment somewhere the customer can actually handle?
Sometimes a different vehicle changes the entire deal.
The customer didn’t suddenly get better credit.
The late payments didn’t disappear. Their income didn’t change.
The car changed.
And because the collateral changed, the structure the lender was being asked to approve changed with it.
That’s a huge distinction.
I am not saying somebody with challenged credit should go buy a more expensive vehicle.
I’m saying the cheapest vehicle on the lot is not automatically the easiest vehicle to finance.
Those are two different things.
If you owe more than the trade is worth, that shortage does not vanish when you buy another car.
If it gets rolled into the next loan, the next lender is effectively being asked to finance the next vehicle plus part of the debt left over from the previous one.
That can push the LTV higher. And at some point, a lender may simply say:
No. Not because the salesperson didn’t work hard enough.
Not because the finance manager needs to “call another bank.”
Not because somebody at the dealership is hiding a secret approval.
The structure may simply not work for that lender.
So now the desk starts moving pieces. Different vehicle.
Different amount financed. Different lender.
Different term. Different cash-down scenario if the customer has one.
Different payment. That is the part customers often never see.
They just know they have been sitting in the dealership for hours and nobody seems to be giving them a straight answer.
I understand why customers hate waiting in a dealership.
Dealerships can absolutely waste people’s time. I’ve worked in this business long enough to know that.
But there are also deals where the store really is working through one problem after another behind the scenes.
The first lender declines it. Another doesn’t like the structure.
Another option still puts the payment too high.
The vehicle doesn’t carry the negative equity.
The desk looks through inventory. Another car gets considered.
The numbers get rebuilt. Another lender looks at it.
A response comes back. Something still has to change.
Meanwhile the customer is sitting there thinking:
What is taking so long?
Then finally the finance manager gets an approval.
The customer walks into the finance office. And the first thing they see is:
Now imagine being on both sides of that conversation.
The customer is thinking:
You kept me here for hours and this is what you came up with?
From finance’s side, the thought may be:
You have no idea how difficult it was to get this approved.
That is the disconnect.
And if the finance manager just says, “This is a good approval, trust me,” I don’t blame the customer for not believing it.
Show them why. Explain what happened.
Explain what was declined. Explain why the vehicle mattered.
Explain what the credit profile looks like to a lender.
Explain why the score they saw somewhere else may not match what was used here.
Explain what their other realistic options are. People handle bad news a lot better when they understand it.
Not because 19.42% is a good rate.
It isn’t. It is expensive borrowing.
It can be a good approval when you compare it with the actual alternatives available on that deal.
If multiple lenders decline the application and one lender finally approves the structure, that approval may be strong relative to what was realistically available.
If the alternatives are no approval at all or a materially higher APR, the same expensive rate means something very different than it does for a shopper comparing it with a much lower approval.
That doesn’t make the interest cheaper. It makes the approval better relative to the situation.
That distinction matters. Expectations can get completely disconnected from reality at this point.
A customer may be comparing the approval in front of them with an advertised low rate they saw online.
But that advertised rate may be available to a completely different credit profile.
Experian’s Q2 2026 used-car averages make that gap pretty clear:
781–850: 6.30% 661–780: 8.77%
601–660: 13.93% 501–600: 19.10%
300–500: 21.62% Again, those are averages.
They are not promises. They are not rate cards.
But they show how dramatically the borrowing environment changes across different credit profiles.
This part matters just as much as everything I just explained.
A dealership getting you approved does not mean you have to buy the car.
A finance manager telling you the approval is strong does not mean you should stop asking questions.
If somebody puts a high-rate approval in front of you, understand exactly what you are signing.
What amount will I actually finance?
What is the term?
What is the monthly payment?
What will the loan cost over the full term?
Do you have another offer from your bank or credit union?
Would a different vehicle improve the structure?
Would money down materially change it?
Can you realistically afford the payment?
And if buying the car can wait, would taking some time to improve the credit situation put you in a meaningfully better position?
Those are fair questions. The dealership should not be afraid of them.
The customer shouldn’t be embarrassed to ask them.
Because the goal should not be: Get somebody into a car at any cost.
The goal should be: Understand the actual situation and make the best decision available from there.
That might mean buying the car. It might mean changing vehicles.
It might mean bringing your own financing. It might mean putting more money down.
And sometimes it might mean not doing the deal today.
When most people see a number that high, they see the rate.
That’s understandable. But the lender may be looking at:
the credit history, the debt,
the income, the amount financed,
the trade, the negative equity,
the vehicle, the collateral value,
the term, the LTV,
and the total risk of the transaction.
The dealership trying to arrange that financing is working inside those same realities.
Both statements can be true at once:
A high APR can be a bad rate and a good approval at the same time.
The rate is expensive.
The approval may still be better than everything else that was actually available.
You deserve to know both.
Because once you understand what happened behind that percentage, you can stop arguing over whether the number looks good and start asking the question that actually matters:
Is this the best workable financing available to me — and does taking it make sense for my situation?
Car shoppers have access to more information than ever.
Credit scores. Rates. Payments. Vehicle values. Trade estimates. Loan calculators.
But having more numbers doesn’t always mean understanding how those numbers work together when it’s time to make the actual decision.
This is the difficult part.
A shopper can know their credit score and still not understand why changing the vehicle can change the approval.
They can know the payment and still not understand what negative equity did to the LTV.
They can know the APR and still not know whether that approval was weak, average, or surprisingly strong for their specific situation.
And the dealership can be working through all of those variables while the customer sees almost none of it.
AutoUnite is being built to help shoppers understand more of the decision before they have to make it — while helping dealers have better conversations with customers who arrive more informed about what actually matters.
Not to tell someone that an expensive APR is a good rate.
Not to tell them to take the deal.
To help them understand why the deal looks the way it does, what questions to ask, and what they should compare before deciding.
Because the percentage matters. But the percentage is not the whole decision.
Research first. Understand the numbers. Then decide what makes sense for you.
Experian’s Q2 2026 data puts the average used-car APR at 11.19% overall, but the averages spread from 6.29% for super-prime borrowers to 21.62% for deep-subprime borrowers. That range is why a single advertised rate cannot explain one customer’s approval.
The shopper still deserves to compare offers, ask what changed the structure and decide whether waiting, adding cash, changing vehicles, using a co-signer where appropriate or improving credit first creates a better result. “Good approval” is a description of what became possible in the lender market—not a command to sign.