Car Buying, Vehicle Research & Ownership Guides
Explore clearer car-buying guidance, market context, and ownership knowledge in one place.

Explore clearer car-buying guidance, market context, and ownership knowledge in one place.
What still has to happen after everyone says yes.
“We agreed to everything thirty minutes ago. What are we still waiting on?”
The customer picked the car. The desk came back with numbers everyone could live with. The trade was agreed to. Everybody said yes.
From the customer’s chair, the deal feels finished.
The wait after “yes” can be the most frustrating part of the visit. Cox Automotive’s shopper study identified waiting or idle time as a major dealership friction point. CDK Global’s 2026 F&I research found that two-thirds of buyers waited to meet with finance, and nearly half waited more than twenty minutes.
The hard part is not always the clock. It is sitting there without knowing what has to happen next.
The store may be waiting on insurance, another dealership, a lender, the trade, the vehicle or information only the customer can provide.
Insurance can be the final thing holding up delivery after everything else is ready.
The customer may already have insurance on the trade. Before the store releases the new car, it needs acceptable proof that coverage is active on the new VIN. Depending on the deal, the proof may also need the correct effective date, covered drivers and lienholder information. Requirements can vary by state, lender, insurer and dealership.
The vehicle can be cleaned and parked at the front door. Finance can have the deal loaded. The keys can be sitting beside the digital signing screen.
The customer is still calling the insurance company.
Sometimes the update takes five minutes. Other times the agent is closed, the app will not accept the VIN, a driver needs to be added, a payment is due or the lienholder is wrong. A customer may send an old card that only shows the trade or a screenshot that does not identify the new vehicle.
Progressive notes that proof of insurance commonly includes policy dates, named insured and vehicle information, including the VIN. Insurers also advise buyers to have proof of coverage available when purchasing a vehicle, while state registration and insurance requirements differ.
Experienced salespeople bring up insurance early. Once the VIN is confirmed, the customer can start the update instead of discovering at the last signature that the insurance card is still wrong.
If the vehicle is on the lot, the salesperson or manager confirms the VIN, finds the keys and makes sure the unit is not sold, held for someone else, in service or attached to another deal.
A dealer trade takes more work.
The locator can show the VIN. The other store still has to agree to release the car.
Someone has to reach the correct manager, confirm the vehicle is physically there and make sure it is still available. Then the stores have to work out what the other dealer wants back.
Do the stores agree on what each vehicle is worth to them, and does the swap still make sense for both sides?
If they agree, they still need drivers or transportation, a workable time and one more availability check before anyone leaves.
Edmunds describes the same basic problem: a dealer can locate the exact color, trim or package, but the other store must be willing to trade, transportation may add time or cost, and there is no guarantee the vehicle will be secured.
The other store may sell the car, stop responding, ask for a different unit back or decide not to release it.
“Getting the deal bought” is dealer language for getting a lender to approve a structure the customer can sign.
CFPB explains dealer-arranged financing as a process in which the dealership can send the application to prospective lenders. A straightforward credit file may receive a quick response. Another deal may need manual review, supporting documents, a lender call or another submission.
For a financed deal, the review generally starts with the credit application, the customer’s credit information and the structure agreed to at the desk.
CFPB says an auto-loan offer can reflect the borrower’s credit history and debts, income, requested loan size and term, down payment, and the vehicle.
The first response may be an approval, a counter or a decline.
A counter means the lender may approve the loan with a different term, more cash down, a lower amount financed or another change. Approvals and counters can also carry stipulations or conditions that must be satisfied before the finance source will fund the contract.
Stips are documents or conditions that have to be cleared. Depending on the lender and the deal, they can include proof of income, proof of residence, bank statements, insurance, an employment check or a customer interview.
“Waiting on finance” can mean two different things.
Finance may be waiting on the bank to review the application, approve stips or issue a final decision.
It may also be waiting on the customer to send a pay stub, unfreeze a bureau, bring in a co-buyer, complete an interview, provide cash down or fix the insurance.
Meanwhile, finance may be working a counter with the desk, moving the application to another lender or trying to keep the customer in the same vehicle without promising terms the bank has not approved.
When the lender participates in an electronic payoff network, the quote can come back quickly.
RouteOne offers an integrated payoff-quote tool for real-time customer-account payoff amounts, and Dealertrack says its payoff tool provides instant quotes from more than 300 lenders.
Other accounts may require a customer call, additional verification or a dated payoff letter.
The dealership may need the payoff to be good through a certain date and the per diem, which is the daily interest added after that date.
The last statement is not enough. The store needs the amount required to close the account when the payoff is sent.
The payoff can come back in minutes while the title still has another owner, an open lien, a name mismatch or someone who is not there to sign.
The worksheet from the sales desk is not the final contract.
The VIN, selling price, trade value, payoff, cash down, lender, term, rate, taxes, fees, address and registration information all have to match.
A lender counter can change the term or money down. A new payoff changes the amount financed. A different VIN can change the book value or program. A corrected address can affect taxes or registration.
Some finance offices run the delivery on a docuPAD® system or another digital F&I system.
The finance manager can review the approved terms, present optional products, answer questions and complete contracts and signatures on the screen. Reynolds and Reynolds describes docuPAD as an interactive F&I menu, electronic signing and eContracting system.
A digital signing system does not help if the approval, insurance, payoff or final numbers are still wrong.
Some documents may still be printed because of the lender, state, store process or customer preference.
The Federal Trade Commission advises buyers to slow down during electronic signing, compare the final deal with what they were told and confirm whether the financing is final before leaving.
The vehicle may need a pre-delivery inspection, state inspection, recall check, software update, detail, fuel, charging, an accessory, a temporary tag or a second key.
A dealer-trade vehicle has to arrive before the store can finish those steps.
Finance may be finished while the vehicle is still in detail. On another deal, the vehicle may be waiting outside while the bank is still reviewing the application.
Both situations look the same from the waiting area: the customer agreed to buy and still does not have the keys.
A bank asking for documents is a real delay. An insurer taking time to update the VIN is a real delay. Another dealership deciding whether it will release a vehicle is a real delay.
Letting the customer sit for forty minutes without an update belongs to the store.
So does waiting until the end to collect information that could have been requested earlier, re-entering details because the handoff failed or discovering an avoidable mistake after the customer reaches finance.
A good process does not mean every customer is gone in thirty minutes. It means the customer knows what step the deal is on, what the store is waiting for and whether anything is needed from them.
“We are waiting on finance” does not answer much.
A useful update sounds like this:
“Your application is at the bank. They asked us to verify income, and we are also waiting for your insurance card with the new VIN. I will check back with you in fifteen minutes even if the status has not changed.”
For a dealer trade:
“The other dealership confirmed the car, but it has not agreed to release it. We are checking a second match so we are not depending on one vehicle.”
The update will not speed up the bank, insurer or other dealership, but it keeps the customer from sitting there guessing.
CDK’s 2026 F&I Buyer Experience reported that 64% of shoppers completed the full purchase process in two hours or less, up from 61% the prior year. CDK also reported a steep satisfaction penalty once the process reached three hours or more: average NPS fell from 29 to 2.
Cox Automotive’s shopper research lands in the same place from another direction. Waiting or idle time ranked as the top friction point. Buyers who were highly satisfied with the dealership experience spent almost 30 fewer minutes at the store and experienced less idle time.
Those figures do not mean every complicated delivery should fit a stopwatch. An outside lender, dealer trade, title problem, stipulation or insurance issue can legitimately add time. They show why unexplained time is not neutral. The buyer experiences the whole visit as one clock even when the dealership is managing several systems at once.
Some waiting produces a result. A lender is reviewing proof of income. The business office is confirming the final approval. The used-car department is obtaining a payoff. The vehicle is being fueled, cleaned or inspected. Another store is releasing a dealer-trade unit.
Dead time feels different: nobody updates the customer, nobody owns the next step, and the customer cannot tell whether ten minutes or another hour remains.
A simple status update changes that experience:
That last line does not make the bank faster. It keeps the customer from disappearing into the process.
When the deal feels done and the clock keeps moving, ask:
AutoUnite is being built so shoppers can research, compare and understand more before they submit their information. Better preparation cannot remove every lender review, insurance update, title issue or dealer trade, but it can reduce avoidable restarts and make the dealership conversation easier to follow.
After you agreed to buy, what part of the remaining wait made sense—and what part never got explained?
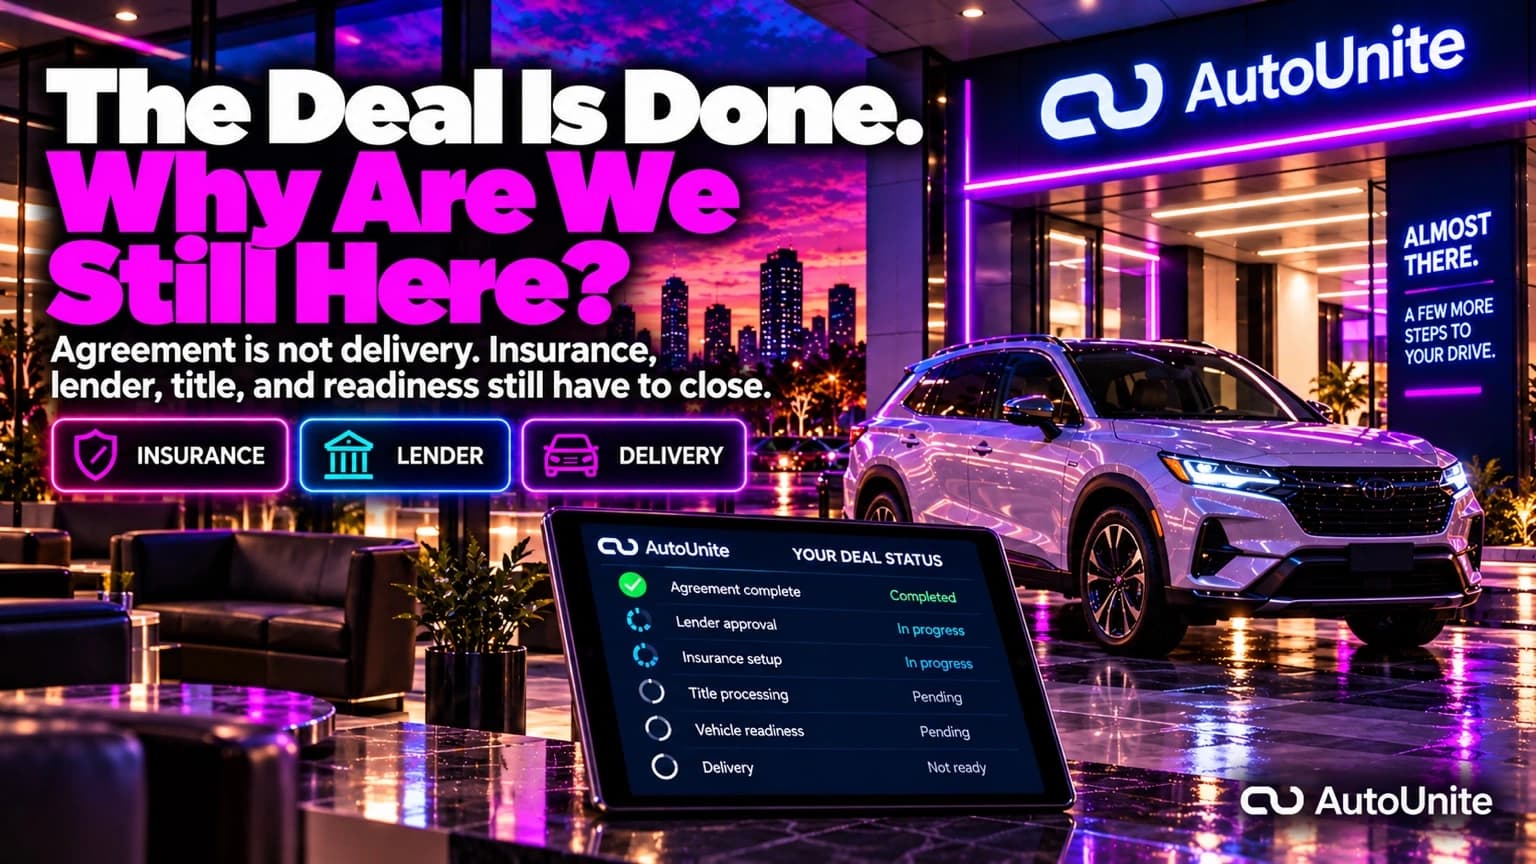
A dealership cannot control every lender response, title issue, insurance hold or dealer-trade decision. It can control whether the customer understands the sequence. The strongest stores turn “we are working on it” into a visible next step: what is complete, what is pending, who owns it and when the next update is coming.
That does not manufacture speed. It removes uncertainty. In a process with several independent systems, clarity is one of the few parts the store can deliver immediately.
AutoUnite content is educational and research-focused. Vehicle information, pricing, ownership costs, maintenance, recalls, and other details may vary by region, dealer, and time.
You agreed on the car and numbers. So why are you still waiting? See what happens next with financing, insurance, trade payoff, F&I and delivery.
Decide First